GEA lifts Q3 orders 20% to EUR 1.65bn and confirms its 2026 outlook
The Düsseldorf machinery group booked almost EUR 300m in large orders, raised its quarterly margin to a record and kept the full-year targets it lifted in July.
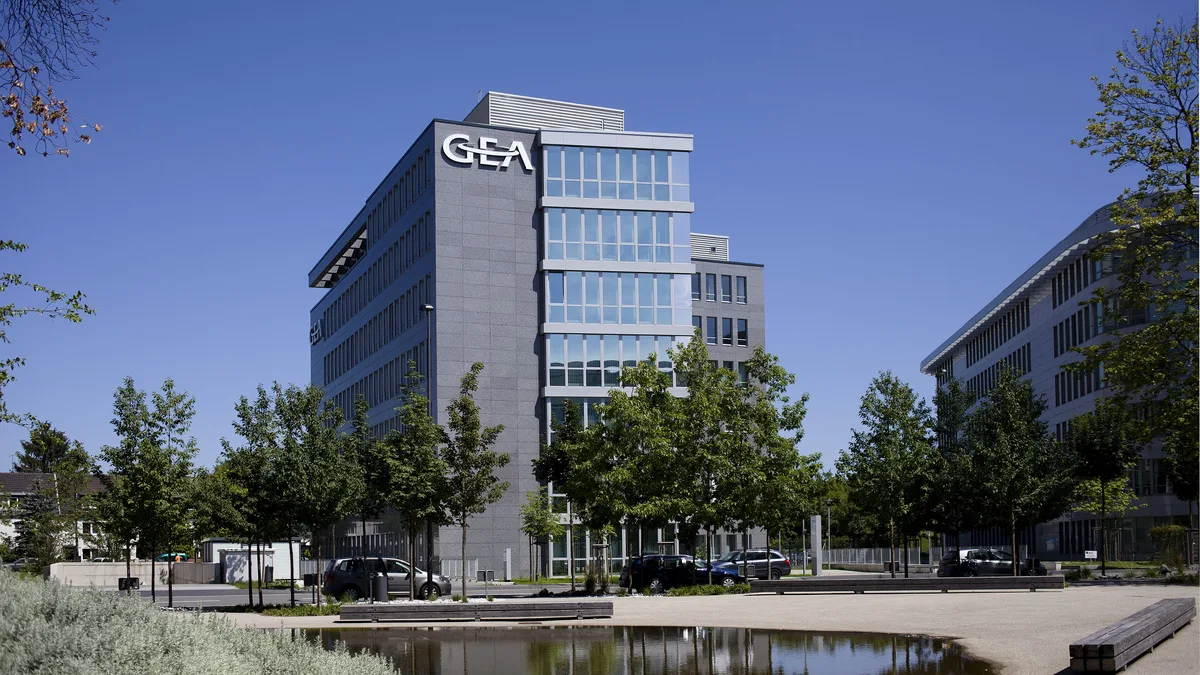
GEA said on 9 November 2026 that third-quarter order intake rose 20.3% to EUR 1,651 million, or 19.5% organically, while revenue grew 7.0% to EUR 1,461 million. EBITDA before restructuring expenses increased 12.6% to EUR 261 million, a record quarterly margin of 17.9%.
The group confirmed its 2026 outlook, raised in July: organic revenue growth of 6% to 8%, an EBITDA margin before restructuring of 17.0% to 17.4% and return on capital employed of 36% to 40%. Handelsblatt and Börsvärlden both highlighted the stronger-than-expected order intake.
Where the orders came from
GEA supplies machinery, process plants and services to the food, beverage and pharmaceutical industries. All divisions contributed to the order growth, with dairy processing, beverage and pharma customers particularly strong. Large orders totalled EUR 294.8 million, compared with EUR 64.4 million a year earlier. EUR 191.7 million of that came from the Nutrition Plant Engineering division and EUR 103.1 million from Pharma & Food Applications.
The order backlog stood at EUR 3.72 billion at the end of September, up 20% on a year earlier, and the book-to-bill ratio was 1.13. That gives the company visibility into 2027.
Continuous tableting as a growth bet
GEA singled out continuous tableting, a technology that produces pharmaceutical tablets in one uninterrupted process instead of separate batches, as especially strong in the quarter. After delivering systems for product development and the first commercial production lines, it booked a large order in the third quarter. Under its Mission 30 strategy, GEA expects this area to grow at 15% to 20% a year through 2030.
Chief executive Stefan Klebert said a 20% rise in orders was "a strong signal" that customers are investing.
Margins, cash and the buyback
Service revenue rose to EUR 597.5 million and reached 40.9% of group revenue. GEA named higher volumes and strong service profitability as the main drivers of the margin gain. Net profit rose 6.4% to EUR 128.5 million, and earnings per share before restructuring expenses climbed to EUR 0.87 from EUR 0.76.
Free cash flow increased to EUR 134.7 million from EUR 52.2 million. GEA ended September with net liquidity of EUR 115.2 million, compared with net debt of EUR 36.3 million a year earlier, despite spending EUR 54.1 million on its share buyback during the quarter. Return on capital employed reached a record 37.8%.
Over nine months, order intake grew 12.3% to EUR 4.6 billion and revenue 6.1% to EUR 4.18 billion.
What it says about European industry
A Dow Jones consensus published before the release had expected order intake of about EUR 1.5 billion, revenue of EUR 1,478 million and EBITDA before restructuring of EUR 264 million. Orders therefore came in well ahead of forecasts, while revenue and EBITDA were slightly below the consensus figures. The order surge matters more for the outlook: it lifts the backlog that will turn into revenue in 2027. Demand for food, beverage and pharmaceutical production equipment depends more on consumption and healthcare than on the industrial cycle, and the order growth suggests producers in these sectors are still investing in capacity and efficiency.
For founders building industrial software, automation or process technology, GEA's growing service share is worth noting. Large equipment makers increasingly earn their margins after the sale, through maintenance, upgrades and digital services, which makes them potential partners or acquirers for startups that improve uptime and yield in the factory. Recent industrial results on the site include Heidelberg Materials and Continental.
Spotted an error? Email contact@europreneursmedia.com and we'll correct it. See our corrections policy and editorial standards.