Qonto becomes a bank after winning a credit institution licence from the ACPR and ECB
Nine years after launch, the business finance platform can take deposits and lend directly. Financing products and term deposits are planned for the first half of 2027.
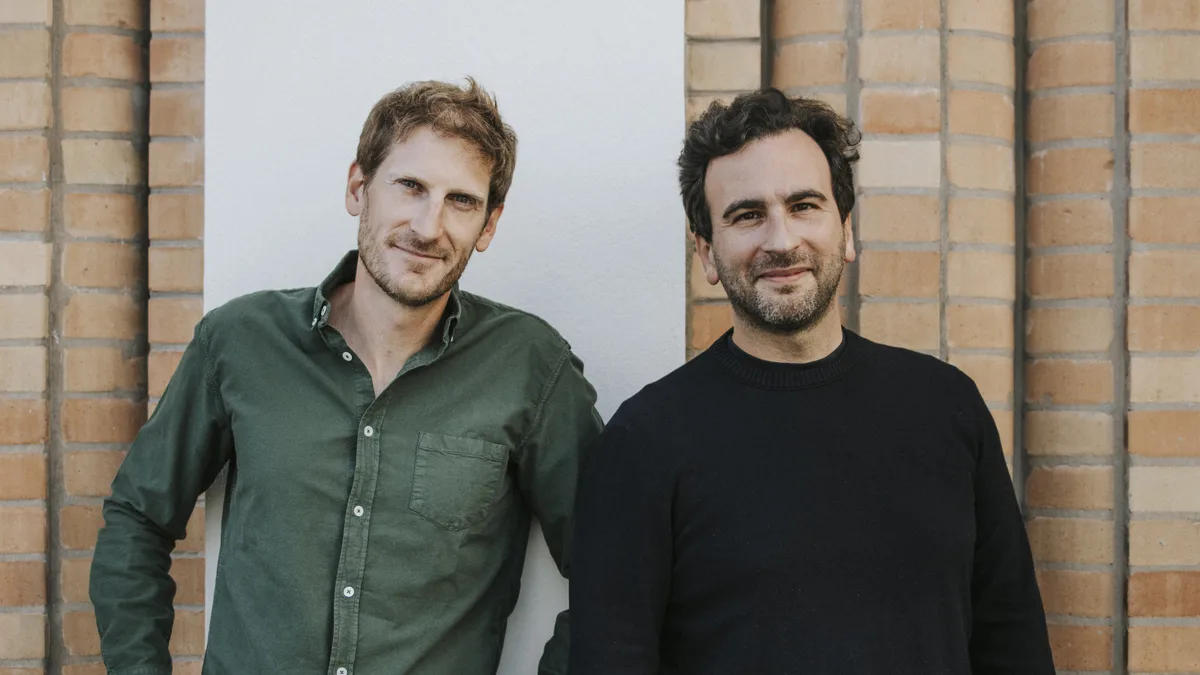
Qonto, the Paris-based finance management platform for small businesses and freelancers, has been granted a credit institution licence by the French banking supervisor ACPR (Autorité de contrôle prudentiel et de résolution) and the European Central Bank, the company announced on 18 November.
The licence lets Qonto progressively extend the lending and savings products it offers directly to European SMEs. The company serves more than 750,000 businesses and freelancers across eight European markets.
From payment institution to bank
Qonto was launched in 2017 by Alexandre Prot and Steve Anavi. It obtained its own payment institution licence in 2018 and has run on its own core banking system since 2019. Since then it has added invoicing, bookkeeping and expense and spend management tools, as well as financing products such as Pay Later, according to the release. It applied for the bank licence in 2025, says it has been profitable since 2023 and employs more than 1,700 people across seven European offices.
According to Qonto's help centre, it has operated as a fully licensed bank since 18 November 2026. Customers' payment accounts become deposit accounts, while their plan, pricing, app and support team stay the same. Cards, transfers, direct debits and IBANs are also unchanged, with the exception of Italian IBANs, the help centre says.
The licence brings Qonto within the European prudential framework for banks, under ACPR supervision inside the ECB's Single Supervisory Mechanism. That means stricter requirements on capital, liquidity, risk management and governance. Eligible deposits are covered by the French deposit guarantee scheme, the FGDR, up to EUR 100,000 per depositor and per institution.
"Too many European businesses still lack access to the financial support they need," said Alexandre Prot, co-founder and chief executive of Qonto. "This license strengthens our ability to support businesses across all aspects of their financial operations, from day-to-day management to financing their growth." He added that the company would remain true to its tech DNA and its scale-up values.
What comes next
Qonto set out an indicative product timeline. In November 2026, it is extending account remuneration to Germany and Portugal and introducing instant capital deposit certificates for company creation in France. In the first half of 2027, it plans a first range of financing products, namely invoice financing, credit lines and loans, as well as term deposits, rolled out progressively across its markets together with services tailored to local needs. The company said the timelines depend on regulatory and operational readiness.
Customers who use Pay Later will see that product replaced by a broader financing offer under a new contract, which also covers cash advances on business customers' invoices. To keep using it after 19 February, they will need to sign the new contract in the app, subject to eligibility, according to the help centre.
The company linked the move to a survey it commissioned of 1,659 solo entrepreneurs and micro-businesses with up to nine employees in France, Germany, Italy and Spain, carried out in March and April 2026. In it, 28 percent said they had missed opportunities because of a lack of financing, and nearly half cited cash-flow management as a major ongoing challenge.
How others see it
Qonto first shared the news in a LinkedIn post on 17 November, PYMNTS reported. The Paypers noted that Qonto has added financing products such as Pay Later since getting its payment institution licence. Les Echos covered the licence in an article headlined with the remark that holding one "remains a club of happy few", describing a banking licence as a grail for fintechs.
Marcel van Oost of the Future of Banking newsletter struck a more cautious note: "The licence is granted, but most of the new products are still on the roadmap." He pointed out that the financing products and term deposits are only due in the first half of 2027 and that Qonto itself calls those dates indicative.
What it means for founders
For small companies and freelancers in Qonto's eight markets, the immediate practical change is deposit protection under the French scheme and, over time, access to credit products inside the tool many already use for banking and bookkeeping. Whether Qonto can price loans competitively against incumbent banks will only become clear once the first products launch.
For the European fintech sector, Qonto joins what Les Echos calls a small club of fintechs with full banking licences, taking on heavier capital and governance requirements in exchange for the right to lend and hold deposits. Recent fintech funding includes Payhawk's USD 280m Series C and Griffin's Series B. More startup news is in our Startups section.
Spotted an error? Email contact@europreneursmedia.com and we'll correct it. See our corrections policy and editorial standards.